 Written by
Advertised balance versus available headroom
Prop firm challenges advertise a nominal account balance, but that number is not your usable room. After losses, your current net equity is what matters. Equity is generally balance plus open position results, adjusted for items such as swaps and commissions, as described in FTMO trading objectives. Daily and overall loss boundaries are separate measures, and you subtract whichever floor is higher at the moment you plan a trade.
A reserve is your own unspent cushion. It is not a firm rule. If you set a reserve of $100, you plan to stop risking before equity reaches that cushion, but the firm’s actual breach boundary sits lower. Reserve exhaustion and a firm breach are different events.
Calculator worked example
The calculator takes your current equity, daily and overall floors, a retained reserve, a fixed planned dollar loss per trade, estimated per-trade costs, and your choice of touch-or-below versus strictly-below boundaries. It reports how many consecutive identical losses fit before your chosen boundary. It does not connect to an account, does not reset floors dynamically, and does not certify compliance.
The following numbers are invented for illustration and are not firm terms. Suppose current equity is $49,600, the daily floor is $49,000, the overall floor is $48,000, the reserve is $100, the planned loss is $100, and estimated costs are $5 per losing trade.
| Item | Hypothetical value |
|---|---|
| Current equity | $49,600 |
| Daily floor | $49,000 |
| Overall floor | $48,000 |
| Reserve | $100 |
| Planned loss plus costs per trade | $105 |
| Headroom above daily floor | $600 |
| Usable planning room after reserve | $500 |
The daily floor is higher, so headroom is $600. After the $100 reserve, usable planning room is $500. Four consecutive losses of $105 each consume $420 and leave equity at $49,180, preserving the reserve. A fifth loss leaves $49,075, below the planning floor of $49,100 but still above the firm’s $49,000 boundary. Reserve exhaustion is not a breach. The calculation assumes floors stay unchanged and no other positions or results occur.
Equality at the boundary
Boundary treatment changes the count. Take hypothetical headroom of $500 with no reserve and a $100 loss including costs per trade. The fifth loss lands exactly on the floor. If your program counts a touch as a breach, only four losses fit. Under a strictly-below rule, the fifth loss exactly touches but does not cross, so it may fit. This is arithmetic, not a recommendation to spend all headroom. Costs and fill variation can remove any assumed equality. There is no universal survival percentage that fits every trader.
Resets, trailing floors and payouts
A static floor stays fixed under its stated rule. A trailing floor updates from its specified high-water measure on its stated schedule, as explained in our pages on drawdown types and trailing drawdown. An end-of-day update does not mean intraday equity stops being monitored. A payout can also reduce your available room depending on product terms. After any reset or payout, check your balances and floors and rerun the calculation rather than reusing a stale number. See daily loss limits for those mechanics.
Converting planned loss to position size
Position size depends on stop placement and your chosen dollar risk, a relation described in CME position sizing. As a concept, stop distance times dollar value per pip, tick or price unit times quantity estimates the price-move loss. Add applicable costs and avoid double-counting spread if it is already reflected. Price value must be in account currency, and quantity rounds down to permitted size increments. A larger stop with the same risk budget implies a smaller quantity. Contract caps and permitted increments remain separate limits.
Aggregate exposure
Open positions and pending orders can overlap, and correlated positions share a risk driver, so they are not necessarily independent bets. Include other potential losses, swaps and costs in your planning. Stop execution is not a guaranteed exact loss. FINRA guidance on stock orders notes that a stop becomes a market order and its execution price can differ from the stop price, while a stop-limit protects price only if filled and may not execute. That guidance covers stock orders, not prop firms. Verify the program’s own execution model for gaps and slippage rather than assuming a stop caps losses exactly.
A practical check before you trade
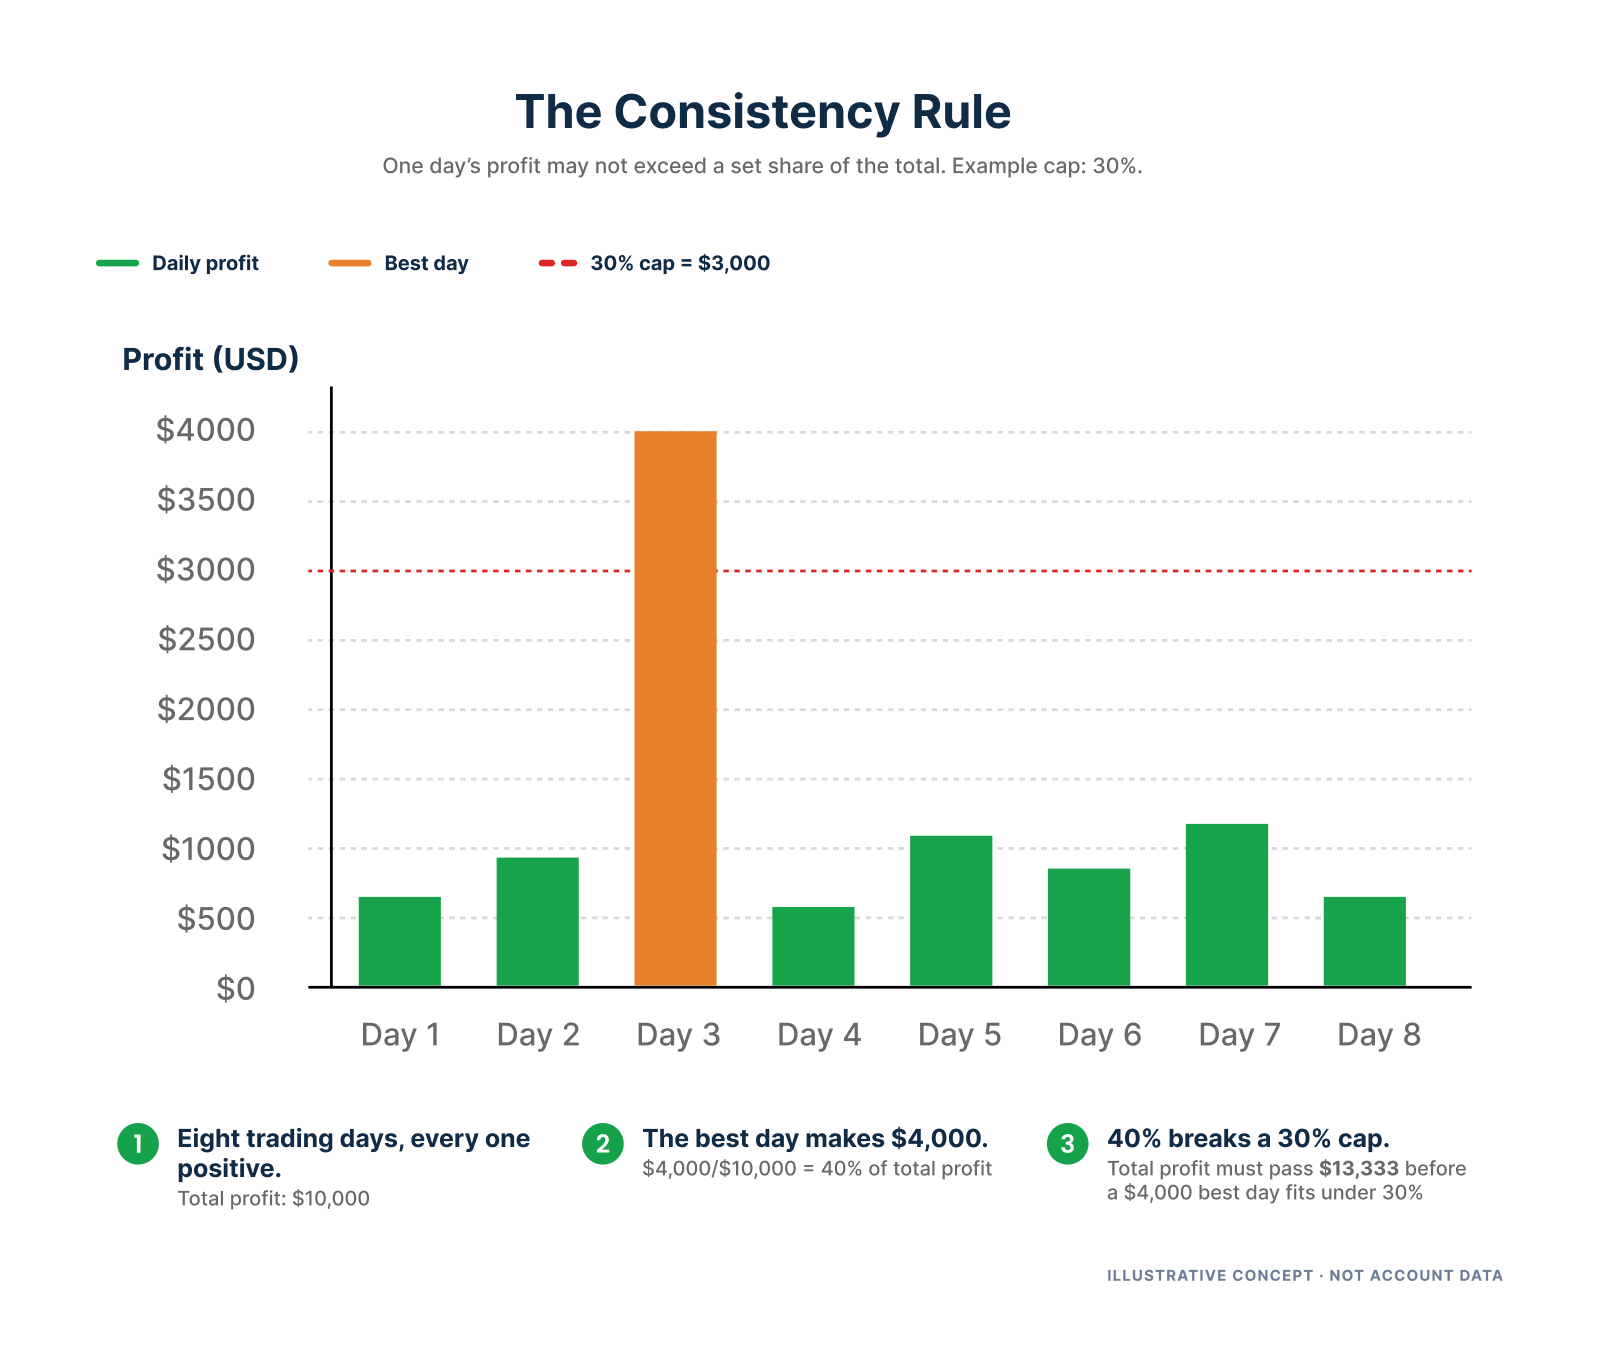
Read your program’s loss rules, record the current floors, and rerun this arithmetic after every reset, payout or rule change. For whether a strategy fits program rules, see strategies. For profit concentration rules, see the consistency rule. For recorded program comparisons by stage, use program comparison.
Frequently Asked Questions
How much risk should I take per trade?
No universal percentage fits every trader and program. Decide a planned dollar loss, subtract it from measured headroom above the applicable floor, and check how many consecutive losses fit. The calculator shows that arithmetic for your entered numbers. It does not recommend a size or guarantee compliance with your firm's terms.
Does a stop order guarantee my maximum loss?
No. A stop can become a market order and fill at a different price, and a stop-limit may not fill at all. Gaps, slippage and platform rules can make the realized loss differ from the planned loss. Costs and swaps add to the total. Check your program's execution model and add a buffer rather than assuming an exact cap.
Why is the headline account size not my available loss budget?
The advertised balance is the starting point. Your usable room is current net equity minus the higher applicable daily or overall floor, and it shrinks after losses. Resets, trailing floors and payouts can also change it. Use current equity and current floors, not the original maximum allowance, when planning.